In this article4
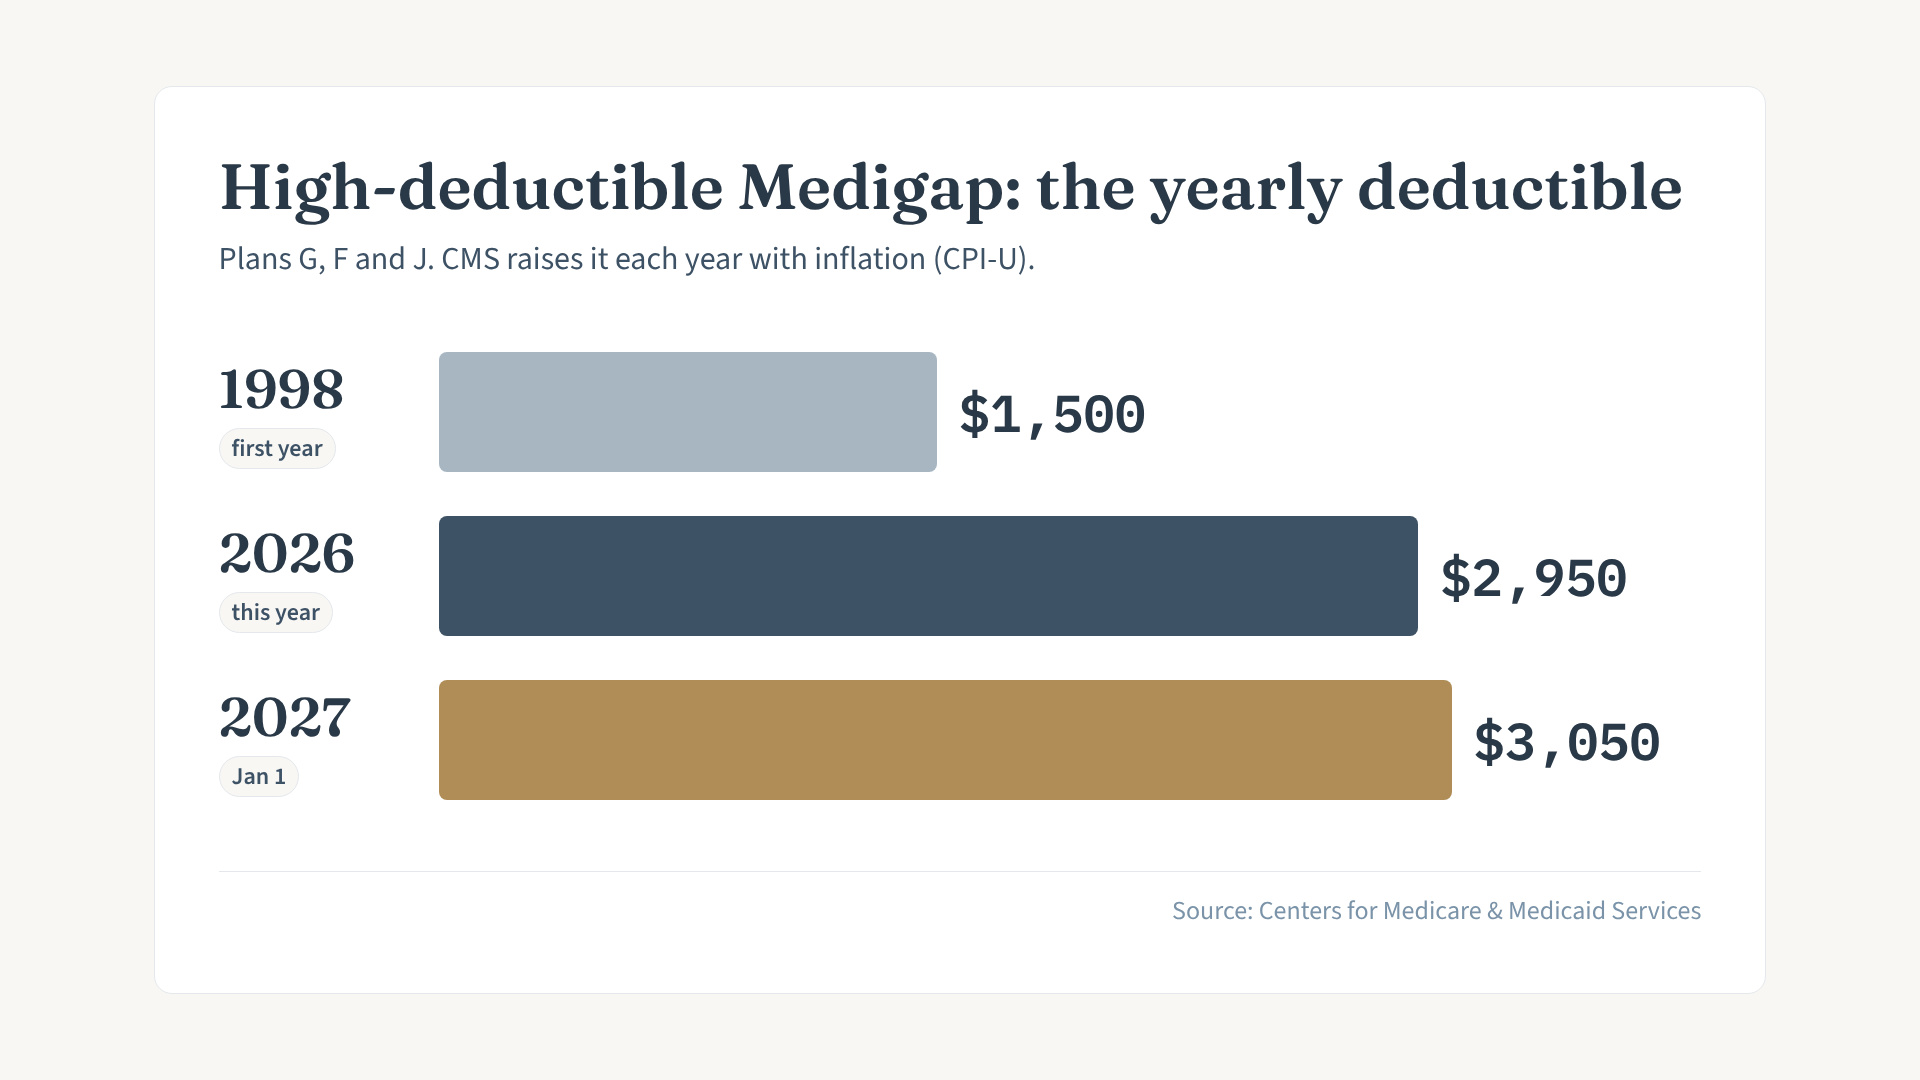
The deductible on high-deductible Medigap plans rises to $3,050 in 2027, up $100 from $2,950 this year, CMS says. If you have one of these plans, or you're weighing one, here's what changes, what doesn't, and how to decide whether it still fits. One thing to know up front is that Medigap doesn't run on the October 15 to December 7 Open Enrollment calendar the way Medicare Advantage and drug plans do. Outside your Medigap Open Enrollment Period or a guaranteed issue right, an insurer can ask health questions and charge you more, as our guide to switching to Medigap in 2027 explains.
📋Quick Summary
- The high-deductible Medigap deductible is $3,050 in 2027, up from $2,950 in 2026.
- The same amount applies to the high-deductible versions of Plans G, F and J.
- You pay Medicare-covered costs, including coinsurance, copayments and deductibles, up to that amount before the policy pays anything.
- High-deductible versions are offered only in some states.
- Plan F, including its high-deductible version, isn't available to people new to Medicare on or after January 1, 2020.
What the 2027 Deductible Is
CMS's announcement is short: "Effective January 1, 2027, the annual deductible amount for these three plans is $3,050." The three plans are the high-deductible versions of Medigap Plans F, G and J. For 2026, the amount is $2,950.
The figure isn't set by insurers. The law behind these plans set the deductible at $1,500 for 1998 and 1999 and tied every later year to the Consumer Price Index for All Urban Consumers (CPI-U). CMS recalculates it each year after the August inflation figures come out and rounds to the nearest $10. For 2027, a 3.4 percent increase in that index produced the $3,050 figure.
How a High-Deductible Plan Works
With a high-deductible plan, you pay for Medicare-covered costs (coinsurance, copayments and deductibles) yourself until you've spent the plan's deductible for the year. Until then, the policy pays nothing. Once you've met it, the policy starts paying. CMS counts your out-of-pocket expenses toward the deductible, but not your premiums.
Our complete guide to high-deductible Plan G walks through how the deductible plays out over a year of care and what it costs compared with the standard plan.
Related Medicare Updates
The deductible rises every year with inflation, so budget for a slightly higher number each January.
Who It Can Suit and Who It Doesn't
Because the policy pays nothing until you reach the deductible, the plan only makes sense if you could cover up to $3,050 in Medicare-covered costs in a year without hardship. A few questions can help you think it through:
- Could you pay $3,050 out of pocket in a bad year, on top of your premiums, without strain?
- How much lower is the premium you're quoted than the standard plan's premium, and how does that difference compare with the deductible?
- Do you expect regular care next year, such as ongoing treatment, a planned surgery or frequent specialist visits?
- Would you rather have a steady, predictable cost, or a lower premium with more risk in a year when you need a lot of care?
If you're choosing a plan for the first time, Plan F isn't an option if you were new to Medicare on or after January 1, 2020. People in that group can buy Plan G instead. If you were eligible for Medicare before then but haven't enrolled, you may still be able to buy Plan F.
How to Compare Before You Switch
Start by checking whether a high-deductible version is sold in your state. Medicare's plan finder lets you look up Medigap policies and prices where you live.
Your best time to buy is your Medigap Open Enrollment Period, which starts the first day of the month you're 65 or older and signed up for Part B. Outside that window, you generally can't switch policies unless you have a guaranteed issue right, and you may have to answer medical questions and pay more. Your State Insurance Department can tell you whether your state gives you more chances to change.
To see how the high-deductible option fits among the standard letter plans, start with our overview of Medigap plans.
If you're also weighing Plan N, see Plan G vs. Plan N.
✅What This Means For You
If you have high-deductible Plan G or F: Your deductible will be $3,050 starting January 1, so plan for $100 more before your policy starts paying.
If you're thinking about switching to one: Compare the premium savings with what you'd pay before the policy pays anything.
If you're outside your Medigap Open Enrollment Period: Expect health questions when you apply, unless you have a guaranteed issue right.
If you're new to Medicare: If a high-deductible plan is sold in your state, Plan G is the version open to you, not Plan F.
Sources
- F, G & J Deductible Announcements — Centers for Medicare & Medicaid Services, Oct 2026
- CY 2026 Medigap High-Deductible Options for Plans F, G and J — Centers for Medicare & Medicaid Services, Oct 2025
- Open Enrollment — Medicare.gov, Undated, accessed Nov 13, 2026
- Can I switch or drop my Medigap policy? — Medicare.gov, Undated, accessed Nov 13, 2026
- Compare Medigap plan benefits — Medicare.gov, Undated, accessed Nov 13, 2026
- Getting Started: Medicare Supplement Insurance (Medigap) — Centers for Medicare & Medicaid Services, Product No. 11575, Mar 2026
- When can I buy a Medigap policy? — Medicare.gov, Undated, accessed Nov 13, 2026
- Find a Medicare plan — Medicare.gov, Undated, accessed Nov 13, 2026
Explore Further
Common questions about the 2027 high-deductible Medigap deductible
- What is the high-deductible Plan G deductible for 2027?
- $3,050, starting January 1, 2027. It's $2,950 in 2026. The same amount applies to the high-deductible versions of Plans F and J.
- Does the deductible include the Part B deductible?
- Yes. Medicare.gov says you pay Medicare-covered costs, including coinsurance, copayments and deductibles, up to the plan's deductible before your policy pays anything. Your premiums don't count toward it.
- Can I still buy high-deductible Plan F?
- Only if you were eligible for Medicare before January 1, 2020. Plans C and F aren't available to people new to Medicare on or after that date. If you already have high-deductible Plan F, you can keep it.
- Why does the deductible go up every year?
- The law that created it set the deductible at $1,500 for 1998 and 1999 and tied later years to inflation (CPI-U). CMS updates it each fall and rounds to the nearest $10.
- Is high-deductible Plan G available in every state?
- No. Medicare.gov says Plans F and G offer a high-deductible version in some states. Your state insurance department or Medicare's plan finder can tell you what's sold where you live.