In this article8
- 01Why Your Card Was Declined at Checkout
- 02What Medicare Flex Cards Actually Cover
- 03Why the Confusion Keeps Happening
- 04What You Should Do Next
- 05When This Becomes a Bigger Issue
- 06How This Connects to Medicare Advantage Plans
- 07How to Avoid This Problem Going Forward
- 08Why This Feels Misleading to So Many People
📋Quick Summary
- If your Medicare flex card was declined at Walmart or another store, it usually means the item you tried to purchase isn't eligible under your plan's benefit rules.
- These cards are not general spending cards—they are limited to specific categories like approved over-the-counter (OTC) items or certain health-related expenses.
- Some plans don't let eligible and ineligible items share one transaction, and some cards decline if run as debit instead of credit.
- Understanding those limits can help you avoid confusion and make full use of the benefit.
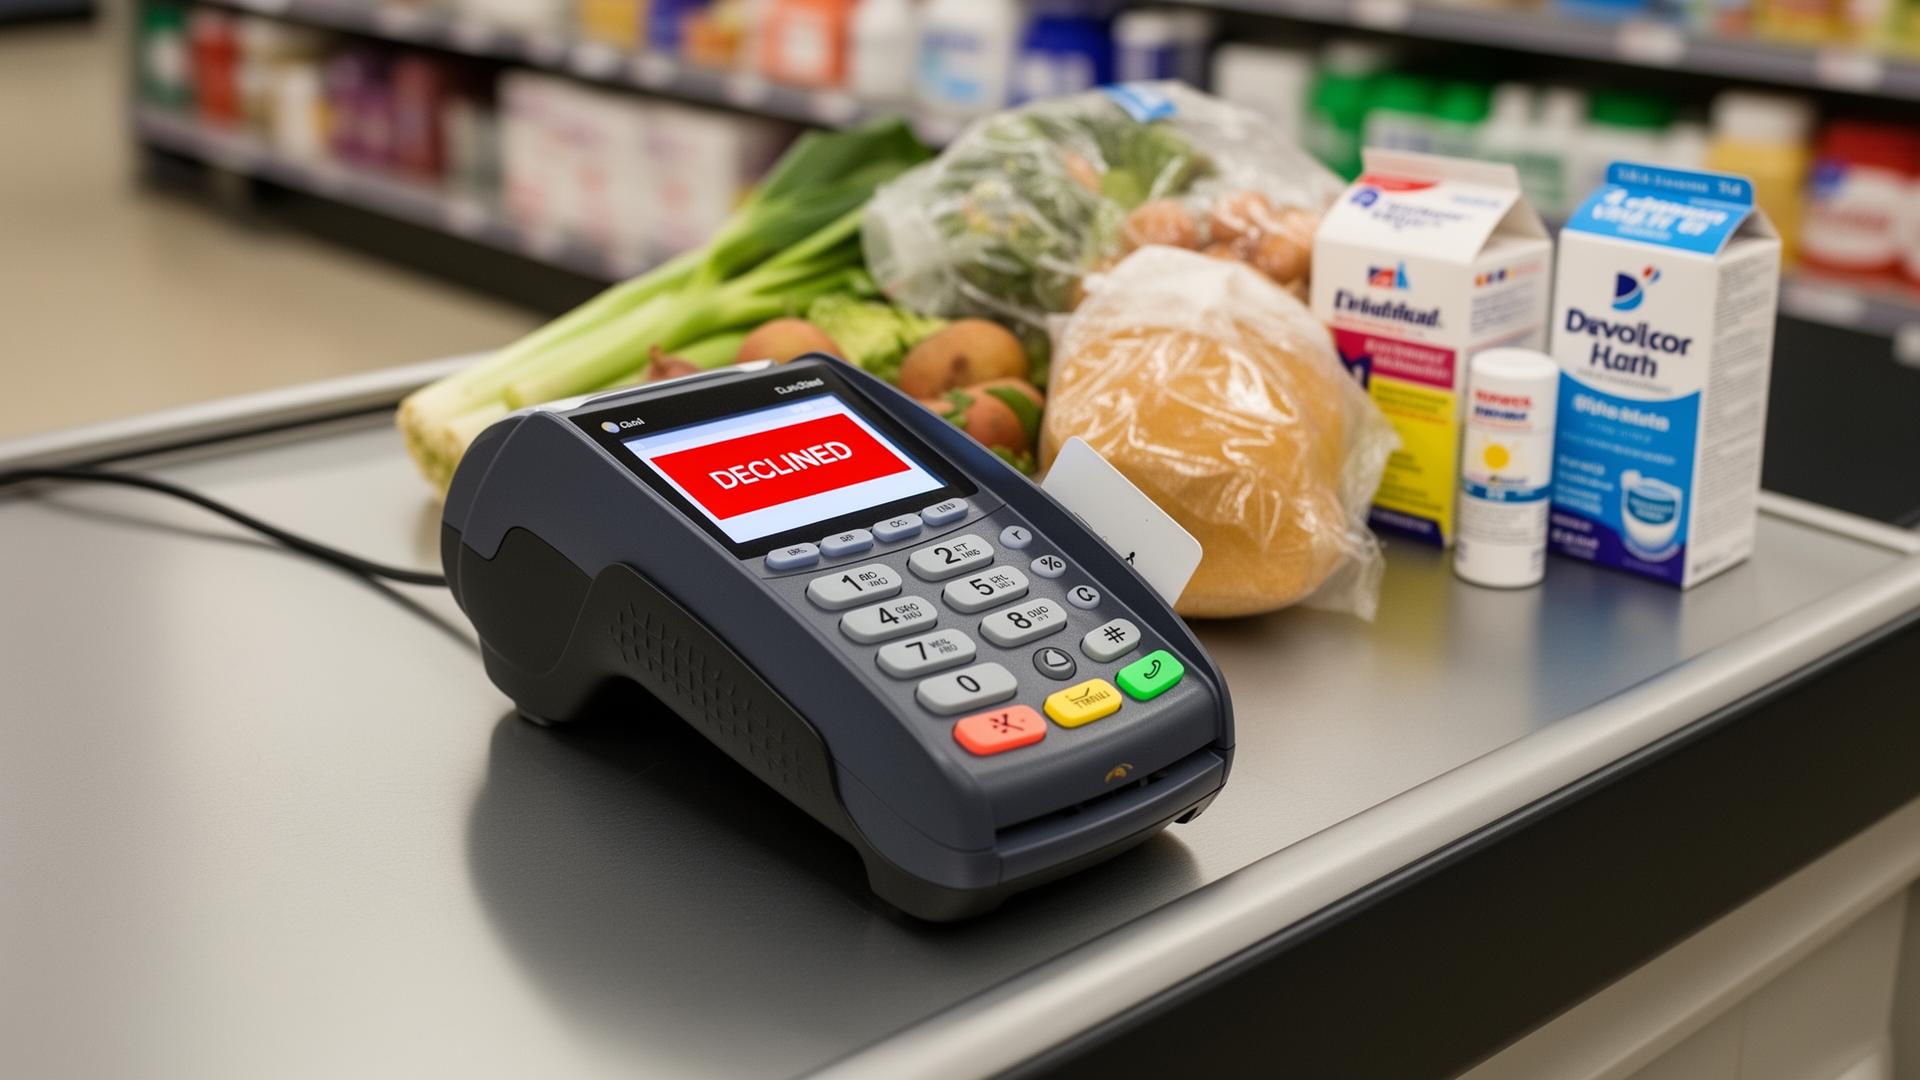
Why Your Card Was Declined at Checkout
If this just happened to you, it can feel frustrating—and confusing. You go to pay, assuming the card works like a debit card, and suddenly it's declined. No explanation, no clear reason.
In most cases, the issue isn't the card itself. It's what you're trying to buy.
Medicare flex cards come from Medicare Advantage plans, and they're restricted-use benefits: they only work on approved items within specific categories.
Mixed carts are a common trigger. Some plans don't let eligible and ineligible items share a transaction at all; one tells members to complete two separate transactions. That's why it often happens at places like Walmart, where a cart holds a mix of eligible and non-eligible products.
The way the card is run matters too. One plan tells members to choose "credit" at the terminal, because selecting "debit" causes a decline.
What Medicare Flex Cards Actually Cover
Despite how they're often advertised, these cards are not "free spending" cards. They typically fall into a few structured categories:
- Over-the-counter health items (like pain relievers, bandages, or cold medicine)
- Some dental care copays
- In some plans, a healthy food allowance—often only for people with certain chronic conditions
The key detail most people miss: each plan defines its own list of approved items, and the scope varies from plan to plan. This is why something that feels "health-related" might still be declined.
If you're trying to understand how these benefits fit into your plan overall, our Medicare Advantage hub explains how the extra benefits are structured.
Related Medicare Updates
Why the Confusion Keeps Happening
These benefits are actually less common than a year ago: KFF found that the share of people in individual Medicare Advantage plans whose plan offers an over-the-counter benefit fell from 79 percent in 2025 to 68 percent in 2026. But the way the cards are marketed hasn't matched how they work.
Many people are seeing:
- Ads falsely claiming Medicare is handing out flex cards worth hundreds of dollars
- Calls that use a card as a hook to move people into a different plan
- Plan summaries that aren't fully clear on restrictions
Medicare itself doesn't issue flex cards. If a text or call offers you one, read our breakdown of the CenturyMed senior card texts before you reply.
So when the card doesn't work at checkout, it feels like something is broken. In reality, it's usually a mismatch between expectations and the plan's actual rules.
What You Should Do Next
If your card was declined, there are a few simple steps that can help you figure out exactly what went wrong.
Start by separating your items: Buy only clearly eligible products (like OTC medications or basic health supplies) in one transaction, and pay for everything else separately.
Ask the cashier to run it as credit: Some plans' cards decline when run as debit.
Next, check your plan's item list: Most Medicare Advantage plans provide a catalog or online list of approved items. This is the most accurate way to know what will work.
You can also check your remaining balance: Some declines happen simply because the benefit has already been used up for the month or quarter. Many plans reset the allowance each quarter, and one plan says unused money doesn't roll over. If an item costs more than your balance, you can ask the cashier to put your available amount on the card and pay the rest another way.
Keep the receipt: Some plans let you pay another way when the card is declined and then request reimbursement with an itemized receipt.
If you're still unsure, contacting your plan directly can clarify what categories your card actually supports. The goal is to remove guesswork—because the card only works when purchases match the plan exactly.
When This Becomes a Bigger Issue
For some people, this isn't just a one-time inconvenience. It turns into a pattern: the card rarely works, purchases are inconsistent, and benefits feel difficult to actually use.
At that point, it's worth stepping back and evaluating whether your plan's benefits are truly meeting your needs. Some plans offer broader or more usable benefits than others, especially when it comes to OTC and supplemental coverage.
If your flex card benefits feel limited, our plan comparison tool can help you weigh plans against how you actually use your benefits. Open Enrollment runs through December 7.
How This Connects to Medicare Advantage Plans
Flex cards are not a standard Medicare benefit—they are offered through specific Medicare Advantage plans. That means:
- Coverage varies by plan
- Eligible items vary by plan
- Benefit amounts and timing vary by plan
Even two people in the same area may have completely different experiences depending on their plan details. Understanding this is key to avoiding confusion—because the card itself isn't universal.
How to Avoid This Problem Going Forward
Once you understand how the card works, it becomes much easier to use effectively. Focus on:
- Shopping from approved item lists
- Keeping purchases simple and category-specific
- Checking balances before shopping
- Avoiding mixed carts with ineligible items
Over time, this turns the benefit from frustrating into useful—but only when it's used within its intended limits.
Why This Feels Misleading to So Many People
The biggest issue isn't the card itself—it's how it's perceived. From a user perspective, it feels like: "I was given a card, so I should be able to use it like one."
But in reality, it functions more like a restricted benefit tool, not a flexible payment method. That gap between expectation and reality is what creates the frustration—and it's why so many people are searching for answers after their first declined transaction.
✅What This Means for You
- If your Medicare flex card was declined at Walmart or another store, it usually means the items you tried to purchase weren't eligible under your plan's rules.
- These cards are limited-use benefits—not general spending cards—and each plan defines what qualifies.
- Understanding those limits and shopping accordingly can help you avoid declines and actually get value from the benefit.
Sources
- Medicare Flex Card Scams: Find Out the Truth — AARP (Kimberly Lankford), Updated Aug 7, 2024
- Medicare Advantage in 2026: Premiums, Out-of-Pocket Limits, Supplemental Benefits, and Prior Authorization — KFF, Jun 5, 2026
- Over-the-counter Benefit — Medical Mutual (plan member page, example), Undated, accessed Nov 11, 2026
- Prepaid Mastercard — Martin's Point Health Care (plan member page, example), Undated, accessed Nov 11, 2026