In this article4
Two numbers will decide whether your January Social Security deposit feels like a raise. The first is the cost-of-living adjustment, which the Social Security Administration announces October 14. The second is the Medicare Part B premium, which comes out of your check before the money arrives and won't be official until CMS publishes it, typically in mid-November. Last year the premium won that contest by a wide margin. Early estimates for 2027 point the other way, but they are estimates, and one of them has a real chance of moving. Here is the math on both, what could knock it off course, and what to do before the numbers are final.
📋Quick Summary
- The Social Security Administration announces the 2027 COLA on October 14 (about 8:30 a.m. Eastern, right after September inflation data). Current estimates run from about 3.2% to 3.6%; The Senior Citizens League projects 3.5%
- The 2026 COLA was 2.8%
- The 2026 Medicare Trustees Report projects a 2027 standard Part B premium of about $209.50, up $6.60 from $202.90 (roughly 3.25%). CMS confirms the official figure, typically in mid-November
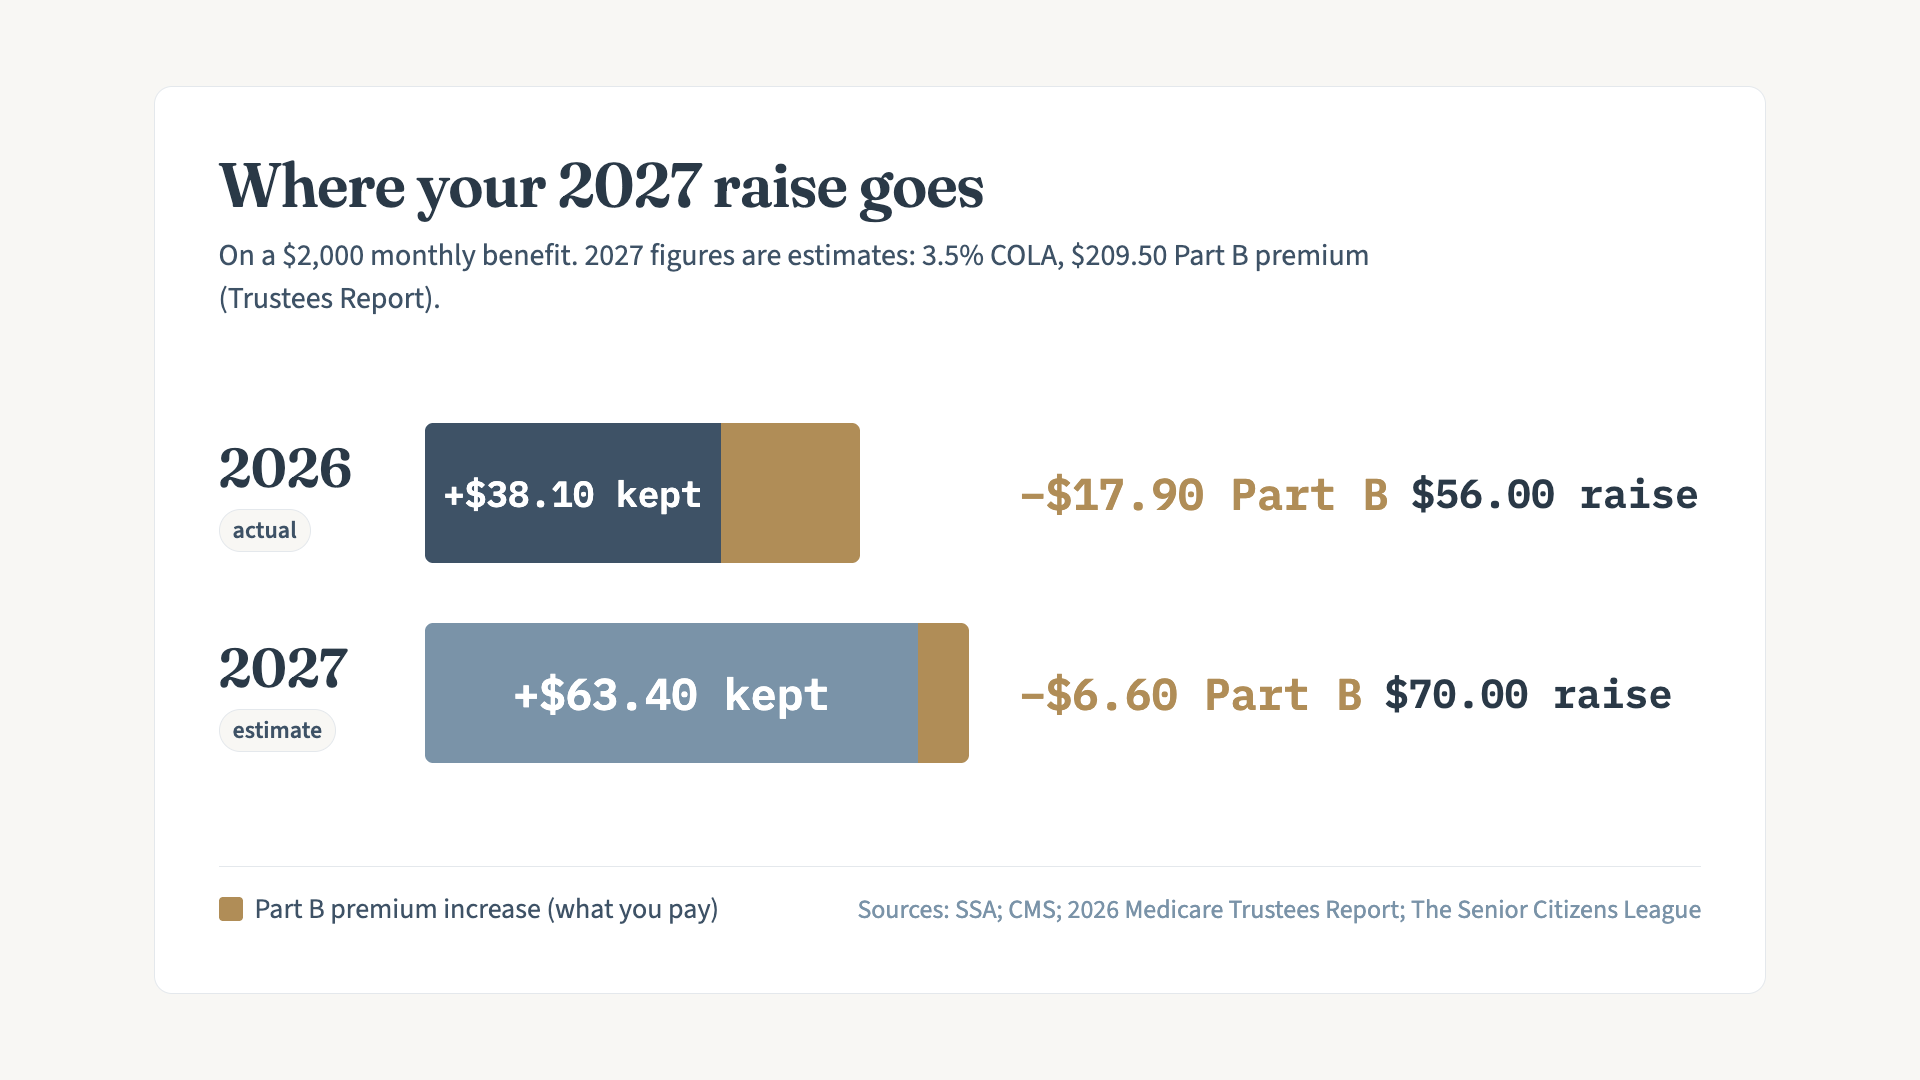
- On a $2,000 monthly benefit, a 3.5% COLA adds $70 and the projected Part B increase takes back $6.60, for a net gain near $63
- Last year, the same $2,000 benefit gained $56 and lost $17.90 to Part B, so the premium absorbed about a third of the raise. This year it would absorb under a tenth
- The Part B deductible is projected to rise from $283 to about $292, but the deductible is paid when you use care, not withheld from your check
- Part D base premiums rise 6% to $41.33 as a federal subsidy program ends; if your Part D premium is also withheld, subtract that too
- Every 2027 number here is an estimate until October 14 (COLA) and mid-November (Part B)
The two numbers, and when each one becomes real
The COLA is calculated from the average of the July, August, and September readings of the CPI-W, the consumer price index for urban wage earners and clerical workers. Two of the three are already in: 3.4% in July and 3.5% in August, both measured year over year. The September reading arrives October 14 at 8:30 a.m. Eastern, and the Social Security Administration announces the official adjustment right after it. The Senior Citizens League currently projects 3.5%, down a tenth from its August estimate. AARP is at 3.6%, and the low end of published estimates sits near 3.2%. For context, the 2026 adjustment was 2.8%.
The Part B side is less settled. The 2026 Medicare Trustees Report projects a standard 2027 premium of about $209.50, up $6.60 from this year's $202.90, an increase of roughly 3.25%. That is far smaller than the 9.7% jump in 2026. But it is a projection, and the Trustees have moved it before: the 2025 report had projected $218.60 for 2027, and we explained in our 2027 IRMAA projection why that older number is out of date. Some private forecasters still expect the final figure to land above the Trustees' baseline, around $216 or higher. The Part B deductible is projected to rise from $283 to about $292. For every 2027 figure in one place, see our 2027 Medicare hub.
Sources: The Senior Citizens League, Kiplinger, The Motley Fool, AMAC
You will see headlines noting that a 3.5% COLA "beats" a 3.25% premium increase. That comparison flatters the situation and hides what matters. Your COLA is a percentage of your whole benefit, while Part B is a flat dollar amount, roughly a tenth the size of a typical check. What lands in your account is the raise in dollars minus the premium increase in dollars. That is why last year's 9.7% premium jump still left most people with a smaller-than-expected raise rather than none at all, and why this year's projected $6.60 increase barely dents a raise of $60 or more.
What a $2,000 check actually looks like
Use a round number to see the pattern. On a $2,000 monthly benefit, last year's 2.8% COLA added $56. The Part B premium rose $17.90, from $185.00 to $202.90, which left a net gain of $38.10. About a third of the raise was gone before it arrived.
For 2027, a 3.5% COLA would add $70. If Part B lands at the Trustees' projected $209.50, it takes back $6.60, leaving a net gain of $63.40. Only about 9% of the raise is absorbed. The average retired worker's benefit was about $2,083 in July, so a 3.5% adjustment would add roughly $73 to that check and net out near $66 after the projected Part B increase.
Now stress the estimate the way a cautious planner would. If the COLA comes in at the low end, 3.2%, and Part B lands near $216 instead of $209.50, the raise is $64, the premium takes back $13.10, and the net is $50.90, with about a fifth of the raise absorbed. That is a worse year than the base case, and it is still better than 2026. The full scenario table is below. These figures cover the standard Part B premium only. They do not include IRMAA surcharges or any Part D premium withheld from your check.
Sources: The Senior Citizens League, TheStreet, our 2026 breakdown
Related Medicare Updates
✅What This Means For You
If you're turning 65 in 2027: You'll pay the full standard Part B premium from your first month of coverage. Build your first-year budget around roughly $209.50 plus any Part D premium, and treat a lower official number as a bonus rather than a plan.
If you're already on Medicare and receive Social Security: Expect two notices in December, one for the COLA and one for the Part B premium. The number that matters is the difference. Once the official figures are out, run your own math: your gross benefit times the COLA, minus the premium increase, minus any Part D premium that is withheld.
If IRMAA affects you: Your deduction is the standard premium plus your surcharge, so your net raise is smaller by that surcharge. Your 2027 tier is already set by your 2025 tax return, as we explain in our IRMAA projection. For the brackets themselves, see our IRMAA income brackets guide.
If you're on Medicare Advantage: Check whether your plan pays part of your Part B premium, the benefit often called a "giveback." Brokers report some insurers are reducing or removing it for 2027, which would take back part of your raise on top of any premium increase. See why 2027 Medicare Advantage benefits are still shrinking.
Explore Further
What could throw the math off
Four things could change the picture before your January deposit. First, the September inflation reading. Two of the three months are already in, so a swing is unlikely, but the estimates have already moved a tenth of a point twice this summer, and the official number is only the average of all three.
Second, the Part B premium itself. The $209.50 projection is the Trustees' baseline, not CMS's final answer. Private forecasters have pointed out that the Trustees have missed in both directions before. If you want a margin of safety, plan around the higher figures in the scenario table rather than the lower ones.
Third, Part D. The federal program that held down standalone drug plan premiums in 2025 and 2026 ends after this year, and the national base beneficiary premium rises 6%, the maximum the law allows through 2029, to $41.33. CMS Administrator Dr. Mehmet Oz has said most people will see increases of less than $10 a month, and some will see decreases; outside analysts, including Avalere Health, are more cautious. If you have your Part D premium withheld from Social Security, any increase comes out of the same check. Our Part D changes page covers the deductible, the out-of-pocket cap, and the subsidy ending.
Fourth, your plan's own changes. Your Annual Notice of Change, due by September 30, will show your 2027 Part D premium and any change to a Part B giveback. Those two lines can move your net more than the Part B projection does.
Sources: CMS fact sheet on 2027 Part D bid information, Managed Healthcare Executive, Medical Daily
What to do between now and mid-November
Start by finding your gross monthly benefit and what is currently withheld for Medicare, both of which are in your online Social Security account. You can't run the math without them. On October 14, write down the official COLA and calculate your raise in dollars. In mid-November, when CMS publishes the official Part B premium, subtract the increase and you have your real number.
In the meantime, open your Annual Notice of Change when it arrives. Our guide to why that September letter matters explains what to check. Then use the enrollment window, October 15 through December 7, to compare drug plans, because the end of the subsidy program makes premiums more plan-specific than they have been. KFF research has found that about seven in ten people with Medicare don't compare plans during open enrollment. Our guide on whether to switch plans before December 7 walks through the decision.
If your Medicare costs are a real strain, check whether you qualify for a Medicare Savings Program, which can pay your Part B premium entirely. Our guide to help with Medicare premiums covers the income limits. We will update this page with the official COLA on October 14 and the official Part B figures when CMS publishes them.
Table 1 — The 2027 numbers and where each stands
| Item | 2026 | 2027 | Status |
|---|---|---|---|
| Social Security COLA | 2.8% (actual) | ~3.5% (range 3.2%–3.6%) | Estimate; official Oct. 14 |
| Standard Part B premium | $202.90 | ~$209.50 | Projected (Trustees); CMS confirms mid-November |
| Part B annual deductible | $283 | ~$292 | Projected; CMS confirms mid-November |
| Part D base beneficiary premium | $38.99 | $41.33 | Final (CMS) |
| Part D deductible | $615 | $700 | Final |
| Part D out-of-pocket cap | $2,100 | $2,400 | Final |
Table 2 — What a $2,000 monthly benefit nets (standard Part B premium only)
| Scenario | COLA | Raise | Part B increase | Net gain | Share of raise absorbed |
|---|---|---|---|---|---|
| 2026 (actual) | 2.8% | +$56.00 | −$17.90 | +$38.10 | 32% |
| 2027 low COLA, Trustees premium ($209.50) | 3.2% | +$64.00 | −$6.60 | +$57.40 | 10% |
| 2027 mid COLA, Trustees premium ($209.50) | 3.5% | +$70.00 | −$6.60 | +$63.40 | 9% |
| 2027 high COLA, Trustees premium ($209.50) | 3.6% | +$72.00 | −$6.60 | +$65.40 | 9% |
| 2027 stress case: low COLA, higher premium ($216) | 3.2% | +$64.00 | −$13.10 | +$50.90 | 20% |
Illustration only. Excludes IRMAA surcharges and Part D premiums. The $216 stress-case premium is the low end of private forecasts, not a CMS figure. Sources: SSA; CMS; 2026 Medicare Trustees Report; The Senior Citizens League.
Answer six quick questions to see which Medicare path matches your health, budget, and timing — Find Your Medicare Path in 60 Seconds →